
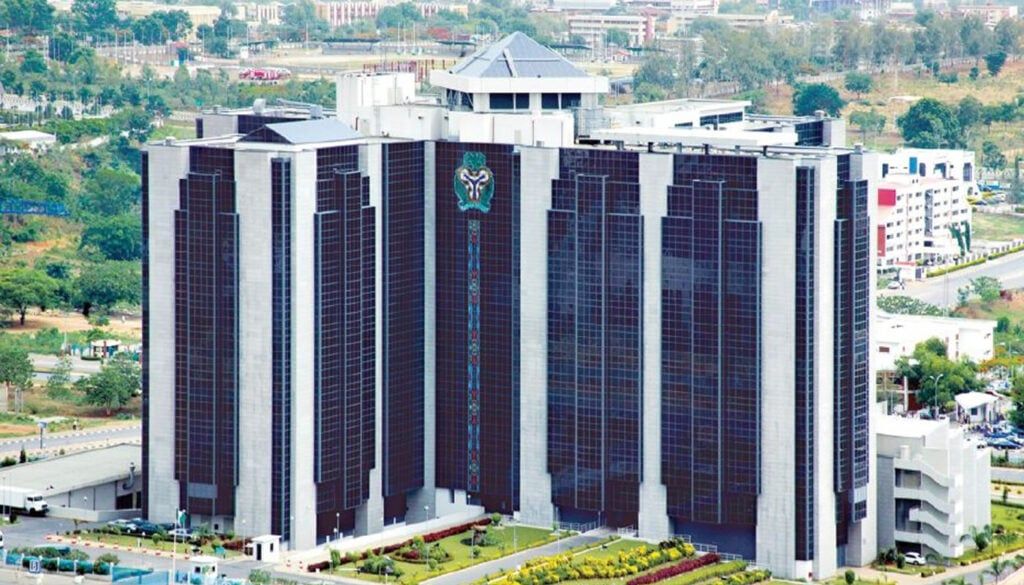
The Central Bank of Nigeria has stepped up its drive to drain excess cash from the banking system.
It pulled out more than ₦90tn through Open Market Operations securities in the first 11 months of 2026, as it works to keep inflation in check ahead of the 2027 general elections.
The amount is far above the ₦40.9tn withdrawn in 2025. It reflects a tougher monetary tightening stance meant to curb surplus liquidity and prevent a fresh surge in prices, amid fears about election-related spending.
The increase in withdrawals comes as policymakers warn that political spending before the 2027 elections could pump large sums into the economy. They say this may complicate the CBN’s efforts to sustain the slowdown in inflation.
According to the apex bank’s 2025 Annual Report, the CBN mopped up ₦50.23tn in 2024, while its sales of OMO securities fell to ₦40.90tn in 2025.
Liquidity absorption has, however, picked up sharply this year. Data from CBN auctions, FMDQ and the Financial Market Dealers Association (FMDA) show that the apex bank withdrew more than ₦90tn through OMO operations between January and November.
The figure excludes OMO maturities for some months, so it may not reflect the net amount of liquidity absorbed during the period.
Monthly FMDA data show that the CBN withdrew ₦13.41tn in January and ₦6.3tn in February.
The amount dropped to ₦2.36tn in March before rising to ₦4.48tn in April.
In May, the apex bank absorbed ₦5.42tn through two OMO auctions held on May 21 and 29, while its mop-up climbed sharply to ₦13.96tn in June.
The amount later eased to ₦7.18tn in July and ₦4.72tn in August.
September recorded the highest OMO allotment, as the CBN raised ₦17.5tn in its push to contain excess liquidity in the banking system.
In October, the apex bank allotted ₦6.182tn in new OMO bills, while ₦9.051tn worth of existing securities matured. According to FMDA data, this left a net repayment of about ₦2.87tn before other adjustments.
The CBN then withdrew ₦7.53tn through OMO auctions held on November 3, 4 and 10.
Some sources put CBN OMO sales at over ₦103tn so far this year. The PUNCH, however, relied on data from CBN auctions, FMDQ and the FMDA.
The heavy issuance comes as the CBN faces the task of maintaining monetary stability while preparing for possible liquidity pressures linked to the 2027 election cycle.
Members of the CBN’s Monetary Policy Committee (MPC) warned in late October that higher government spending ahead of the 2027 general elections could fuel inflation, weaken fiscal discipline and complicate efforts to keep monetary conditions stable.
The warnings came as Nigeria’s broad money supply rose to ₦146.60tn in September 2026, up ₦28.82tn from a year earlier, while credit to the government grew by 63.09 per cent to ₦39.40tn.
The concerns were contained in personal statements issued by MPC members after the committee’s 307th meeting, held on September 21 and 22, 2026.
The members cautioned that election-related expenditure, together with pressure from fuel, food and production costs, could slow the country’s progress in bringing inflation under control.
Deputy Governor of the CBN’s Corporate Services Directorate, Dr Muhammad Abdullahi, warned that election-related fiscal expansion could transmit inflationary pressure through transportation, energy and production costs.
“I recognise that election-related fiscal expansion and other incipient price pressures may propagate through transport, energy and production cost channels, amplifying economy-wide cost-push inflation,” he said.
Abdullahi called for closer coordination between fiscal and monetary authorities, to stop government measures from injecting extra liquidity into the economy and undermining price stability.
Another MPC member and Senior Fellow at the Brookings Institution, Dr Aloysius Ordu, urged the government to maintain fiscal discipline as political activities intensify.
“And as the election cycle approaches, stronger safeguards against fiscal slippage and pro-cyclical spending will be important,” Ordu said.
He noted that improved oil receipts were strengthening government finances. He warned, however, that converting foreign exchange earnings into domestic liquidity could complicate efforts to contain inflation.
MPC member Bandele Amoo also identified political activities and budget implementation as possible sources of renewed spending pressure.
“As global uncertainty remains elevated, domestic political activities may introduce new spending pressures, and supply-side vulnerabilities continue to pose risks to the inflation outlook,” Amoo said.
He expressed optimism that better coordination between the CBN and the Federal Ministry of Finance would help manage spending pressures. He stressed that monetary policy decisions should remain guided by economic evidence and medium-term price stability.
Professor Murtala Sagagi acknowledged that election-related spending had historically pressured demand and prices, but said existing monetary policy tools could help contain the risks.
He cited the CBN’s liquidity management instruments, its Cash Reserve Requirement and a memorandum of understanding on fiscal-monetary coordination between the CBN and the Federal Ministry of Finance.
CBN Governor, Olayemi Cardoso, said the bank had studied previous election cycles and developed scenarios to prepare for possible liquidity pressures.
“We are ready,” Cardoso said at a press briefing after the committee’s September meeting.
He said the bank would monitor currency in circulation, banking system liquidity, monetary aggregates and foreign exchange demand.
“We will proactively deploy any tools and instruments to mop up any excess liquidity,” the governor said, adding that the CBN would not allow itself to be caught unprepared.
The World Bank warned in October that Nigeria’s consolidated fiscal deficit was expected to widen from 3.1 per cent of GDP in 2025 to 3.5 per cent in 2026, despite higher oil revenues and increased government allocations.
In its Nigeria Development Update, titled ‘Beyond the Federal Purse: How Higher Revenues Reshaped State Priorities’, the bank said stronger capital spending and pre-election spending would outweigh the gains from increased revenues.
“Despite the narrower federal fiscal deficit in H1 2026, stronger capital spending by states alongside rising federal personnel, interest, and pre-election spending is expected to widen the consolidated fiscal deficit from 3.1 percent of GDP in 2025 to 3.5 percent in 2026, outweighing stronger revenues,” the World Bank said.
The report said higher oil prices, following the conflict in the Middle East, had supported government revenues and improved the country’s external position. It added that existing oil sales and financing commitments had limited the fiscal benefits.
The bank warned that spending pressures are expected to increase later in the year, potentially reversing some of the fiscal gains.
Economists have attributed the CBN’s aggressive liquidity mop-up in 2026 to higher election-related spending and bigger revenue allocations to state and local governments. They said the exercise reflects the apex bank’s efforts to stop excess money in circulation from triggering fresh inflationary pressures.
In separate phone interviews with The PUNCH, the economists said rising government revenues, growing public sector deposits in commercial banks and political spending had contributed to the liquidity build-up. This left the CBN with the task of absorbing surplus funds.
A Professor of Economics and Public Policy at the University of Uyo, Akpan Ekpo, said the CBN was seeking to control money supply to prevent excess liquidity from undermining price stability.
“With the election coming, there will be a lot of expenditures. So, the CBN has to mop it up because even inflation is not always a monetary phenomenon; it can also be a fiscal phenomenon,” Ekpo said.
He explained that the apex bank was worried that excess cash in the financial system could translate into higher consumer spending and push up prices.
“I suspect the CBN wants to make sure that the liquidity in the system does not jack up the consumer price index,” he said.
Ekpo, however, doubted the effectiveness of the intervention, arguing that the scale of spending expected before the elections could undermine the CBN’s efforts.
“With the elections coming, I don’t think the CBN effort will bear much fruit,” he said.
Similarly, the Founder of the Centre for the Promotion of Private Enterprise, Dr Muda Yusuf, linked the liquidity expansion to increased government revenues and allocations to state and local governments, much of which he said remained within the banking system.
“The only source that I think could have been responsible for that is the high government revenue resulting from higher allocations to the state and local governments, most of which are also in the banks,” Yusuf said.
He noted that the CBN had introduced differentiated cash reserve requirements to limit the amount of public sector funds banks could deploy for lending.
The apex bank imposes a 75 per cent Cash Reserve Ratio on public sector deposits outside the Treasury Single Account, compared with 45 per cent on regular deposits.
Despite these restrictions, Yusuf said public sector funds continued to add to overall liquidity in the financial system.
“The public sector liquidity is feeding into the financial system liquidity,” he said.
He also identified election-related expenditure as another source of pressure. He noted that spending by political parties, candidates and government institutions involved in the electoral process could inject huge sums into the economy.
“Political spending from INEC, security agencies, political parties and, above all, the candidates themselves, all of those things are injecting a lot of liquidity into the system,” Yusuf said.
The Managing Director of Highcap Securities Limited, Mr David Adonri, also named monetary operations, bank recapitalisation and government spending as factors that could have contributed to the liquidity build-up.
He explained that transactions involving OMO securities could affect the volume of funds available in the banking system, particularly when the CBN redeems previously issued instruments.
Adonri also noted that a reduction in banks’ holdings of certain securities could have left them with more funds to deploy, while the recapitalisation exercise boosted the capital available to financial institutions.
He further linked the liquidity situation to political activities, arguing that increased spending by governments and politicians could add more pressure to the financial system.
According to him, when investors redeem government securities, the proceeds return to the banking system, potentially raising available liquidity, particularly where the instruments carry high yields.