
The National Pension Commission is intensifying efforts to bring more self-employed and informal sector workers into the pension system.
An estimated 84.9 million Nigerians remain without pension coverage, a major gap in the country’s retirement security system.
The figures were presented at the 2026 Annual PenCom Media Conference in Lagos.
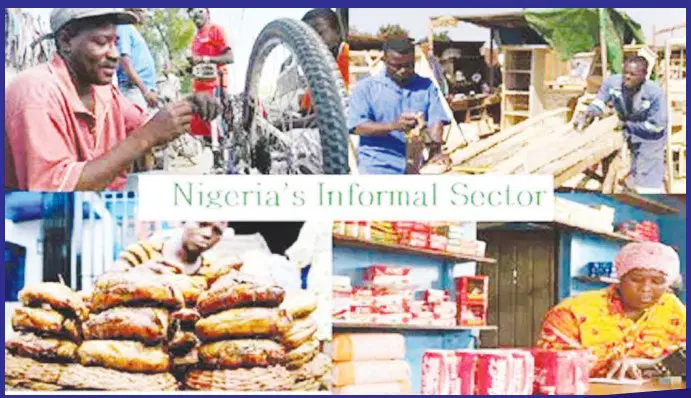
They showed that the informal sector accounts for an estimated 93 per cent of Nigeria’s workforce. However, only 242,690 informal sector workers had enrolled in the Personal Pension Plan (PPP) as of July 2026.
Based on estimates of the informal sector workforce, this puts pension coverage among the group at just 0.29 per cent. The figure underscores the challenge of bringing millions of traders, artisans, farmers, professionals and gig workers into the pension system.
The Personal Pension Plan was introduced under Section 2(3) of the Pension Reform Act (PRA) 2014. It is meant to extend pension coverage to self-employed persons and informal sector workers who may not have access to conventional employer-sponsored retirement savings arrangements.
Under the scheme, eligible contributors can make flexible payments daily, weekly, monthly or at their convenience, depending on their income and circumstances.
Registration requires a National Identification Number (NIN) and a phone number. Prospective contributors can register directly with a Pension Fund Administrator (PFA) or through an accredited pension agent.
The presentation identified several obstacles to wider participation. They include irregular earnings, limited awareness, distrust of financial institutions, a preference for readily accessible savings, geographical barriers and gaps in digital literacy.
For many informal sector workers, whose earnings can fluctuate considerably, saving for retirement is difficult when contributions compete with immediate household and business expenses.
The presentation also noted that having a pension account does not necessarily lead to sustained savings, as some contributors register without making regular or subsequent payments.
It stressed that the success of the Personal Pension Plan should therefore be judged not only by the number of registered accounts. It should also be judged by the number of active contributors, frequency of contributions, consistency of saving, average account balances and the adequacy of retirement benefits.
Under the Plan’s contribution structure, 50 per cent of contributions forms the contingent portion. This can be withdrawn three months after the initial contribution and subsequently once every two months.
The remaining 50 per cent is set aside for retirement benefits. It can be accessed from age 50, or earlier in cases of medical incapacitation, subject to applicable regulations.
To widen participation, PenCom has accredited pension agents to take the scheme closer to underserved communities and workers with limited access to conventional pension services.
The agents are expected to facilitate enrolment, support contributions and account updates through approved channels, and carry out public sensitisation and financial literacy activities.
The presentation listed six approved pension agents that received accreditation on three dates in 2026. Awabah Remit Services Limited was accredited in February, while e-Tranzact International Limited and NextAutomate APA Limited were accredited in June.
SunTrust Bank Nigeria Limited, PrimeTrust APA Limited and Majestic APA Limited were accredited in September.
The presentation further identified financial literacy, trust-building, convenient payment channels and contribution arrangements suited to irregular earnings as key areas for improving participation and encouraging long-term saving.
It also highlighted the gender dimension of the challenge, citing an estimate that 96 per cent of employed women work in the informal sector. This makes expanding pension coverage particularly relevant to women whose livelihoods fall outside formal employment.
Beyond increasing enrolment, the commission’s challenge is to ensure that workers remain active contributors and build up enough savings to support them in retirement.
The presentation concluded that expanding access alone would not close Nigeria’s pension gap. It said sustained participation, consistent contributions and adequate retirement balances are essential to making the Personal Pension Plan a meaningful source of financial security for the country’s vast informal workforce.